2
Nov
XAUUSD Weekly Outlook: June Floor Breaks as Election and NFP Week Begins (Week of November 2, 2026)
Where price stands
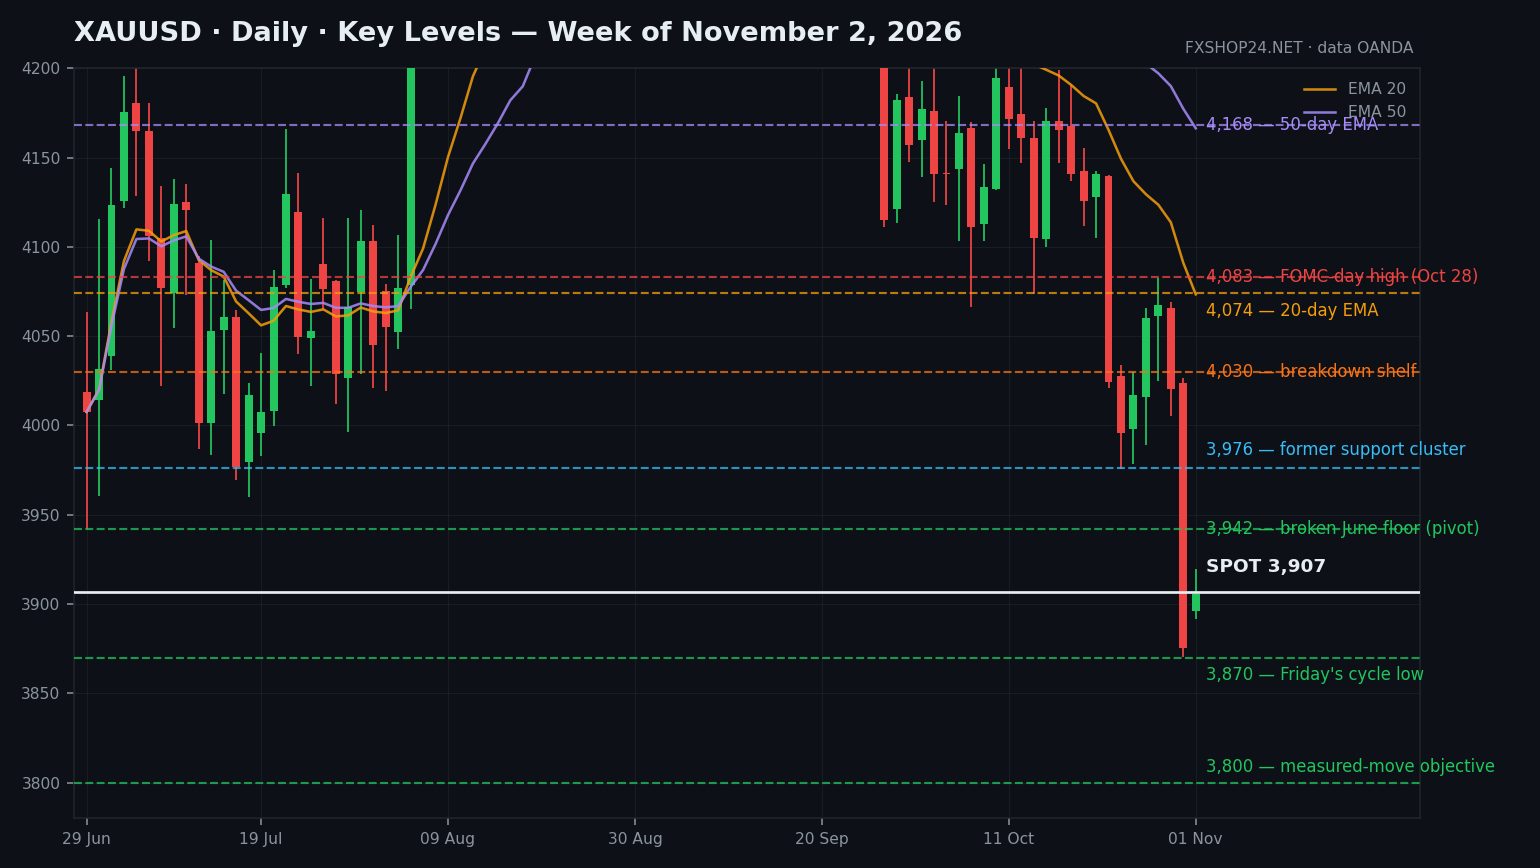
Spot gold trades around 3,907 on Monday morning (November 2), trying to stabilize after a brutal end to October. The sequence since our last outlook: Wednesday’s FOMC held rates at 3.75–4.00% in a split vote (Hammack and Cook dissented in favor of a hike), and Chair Warsh — saying the “monetary medicine” is working while neither promising nor ruling out a December move — was read as slightly less urgent than feared. Gold popped to 4,083 on the day, its best level of the week. Then the data landed: September PCE (Thursday) showed headline inflation at 3.6% with core at 3.1% and core services ex-housing at 3.6%, the hottest since 2024. December hike pricing firmed again, and on Friday gold collapsed — a $154 range (4,027→3,870), −3.6% on the day, closing the week at 3,876, its lowest since June.
That Friday close matters more than any single number: gold finished the week below the June 29 low of 3,942 — the structural floor that had contained the entire four-month correction from the May peak at 4,774. The “correction vs trend change” question we have tracked for months is now answered in price: the trend has changed to down, and the 20-day EMA (≈4,074) and 50-day EMA (≈4,168) are overhead resistance. The bullish counterweights are real but unproven: positioning is stretched short, central banks keep buying, and the metal is deeply oversold relative to its 200-day average. Monday’s early trade (3,891–3,919) is the market deciding whether Friday was capitulation or the start of the next leg.
Key levels
| Level | Type | Why it matters |
|---|---|---|
| 4,168 | Resistance | 50-day EMA — the bear-market line of the whole correction; far overhead |
| 4,083 | Resistance | FOMC-day high (Oct 28) and last week’s high — the “Warsh relief” ceiling |
| 4,074 | Resistance | 20-day EMA, falling fast — dynamic resistance on any bounce |
| 4,030 | Resistance | Breakdown shelf: Oct 26 high (4,030) and the Oct 29–30 closes (4,021–4,027) |
| 3,976 | Resistance | The former support cluster (Oct 23–27 lows at 3,976–3,989) — broken support turns supply |
| 3,942 | Pivot | The broken June 29 floor — polarity flip; a reclaim is the minimum required to stabilize the picture |
| 3,870 | Support | Friday’s new cycle low (Oct 30) — must hold on a closing basis or the decline extends |
| 3,800 | Major support | Round number / measured-move objective; below it, 3,750 is the bank-flagged bear target |
Two scenarios
Bearish (base case while below 3,942): the June floor broke on a weekly close, the Fed’s December meeting is priced as live (futures lean to a hike on December 8–9), and the dollar remains firm. If Friday’s low gives way, the path runs to 3,800 and then 3,750; a firm jobs report on Friday (consensus +55k, wages +0.3%) would accelerate it. Invalidation: a daily close back above 3,976.
Bullish (oversold relief rally): Friday had the fingerprints of liquidation — a $154 flush, deeply stretched positioning, and persistent official-sector buying underneath. If 3,870 holds on a closing basis and the market gets a catalyst (a soft NFP, election-night uncertainty hitting the dollar, or Middle East escalation), short-covering through 3,942 and 3,976 targets the 4,030 shelf; only above ~4,080 would the damage start to look repaired. Invalidation: a daily close below 3,870.
Calendar watch
- Monday, November 2: ISM manufacturing (10:00 am ET, consensus ≈54.7); final global PMIs. Note: US clocks went back on Nov 1 — 8:30 am ET is now 14:30 CET.
- Tuesday, November 3: US midterm elections (all 435 House seats, 35 Senate seats; markets open as usual) — expect headline-driven swings and thin evening liquidity; JOLTS job openings (10:00 am ET); RBA decision overnight.
- Wednesday, November 4: ISM services (10:00 am ET, consensus ≈54.7); ADP private payrolls (8:30 am ET); eurozone flash CPI; US Treasury quarterly refunding announcement.
- Thursday, November 5: weekly jobless claims (8:30 am ET); Bank of England decision (a first hike in the cycle is expected) — a global-rates story that can spill into gold via yields.
- Friday, November 6: October nonfarm payrolls (8:30 am ET) — consensus +55k after September’s +29k, unemployment 4.2%, average hourly earnings +0.3%. The last major input before the December FOMC; University of Michigan prelim (10:00 am ET).
- Forward markers: October FOMC minutes on November 18; the December 8–9 FOMC (with new dot plot) is the next live rate decision.
EA angle
- Volatility regime: headline ATR is ~$71, but Friday alone printed a $154 range — this is an expansion regime. Plan for $80–120 daily ranges into NFP; widen stops and grid steps rather than trusting the quiet-October norms.
- News filters: two must-filter events — ISM services Wednesday and NFP Friday 8:30 am ET (14:30 CET). Election night (Tuesday) carries headline risk in thin liquidity; consider standing aside late Tuesday US time even without a scheduled release.
- Trend vs mean-reversion: trend-followers finally have the wind at their backs (broken floor, falling EMAs, live December-hike pricing) — but the quality entry is a bounce that fails into 3,942–3,976 supply, not a chase into 3,870. Mean-reversion longs only against 3,870 with confirmation (rejection wick + reclaim of 3,900); no blind knife-catching below the broken floor.
- Sizing: halve risk through Friday. Election week plus NFP means gaps and stop slippage well beyond backtest norms; the December FOMC is the real event, so think in terms of surviving this week with dry powder.
FXShop24 Research Team — educational content, not investment advice. Trading gold? Read our guides on position sizing and gold-specific EA settings on fxshop24.net, and follow @fxshop24 on Telegram for weekly levels and free signals.