16
Nov
XAUUSD Weekly Outlook: Hot CPI and Hawkish Fed Talk Send Gold Back Below the June Floor (Week of November 16, 2026)
Where price stands
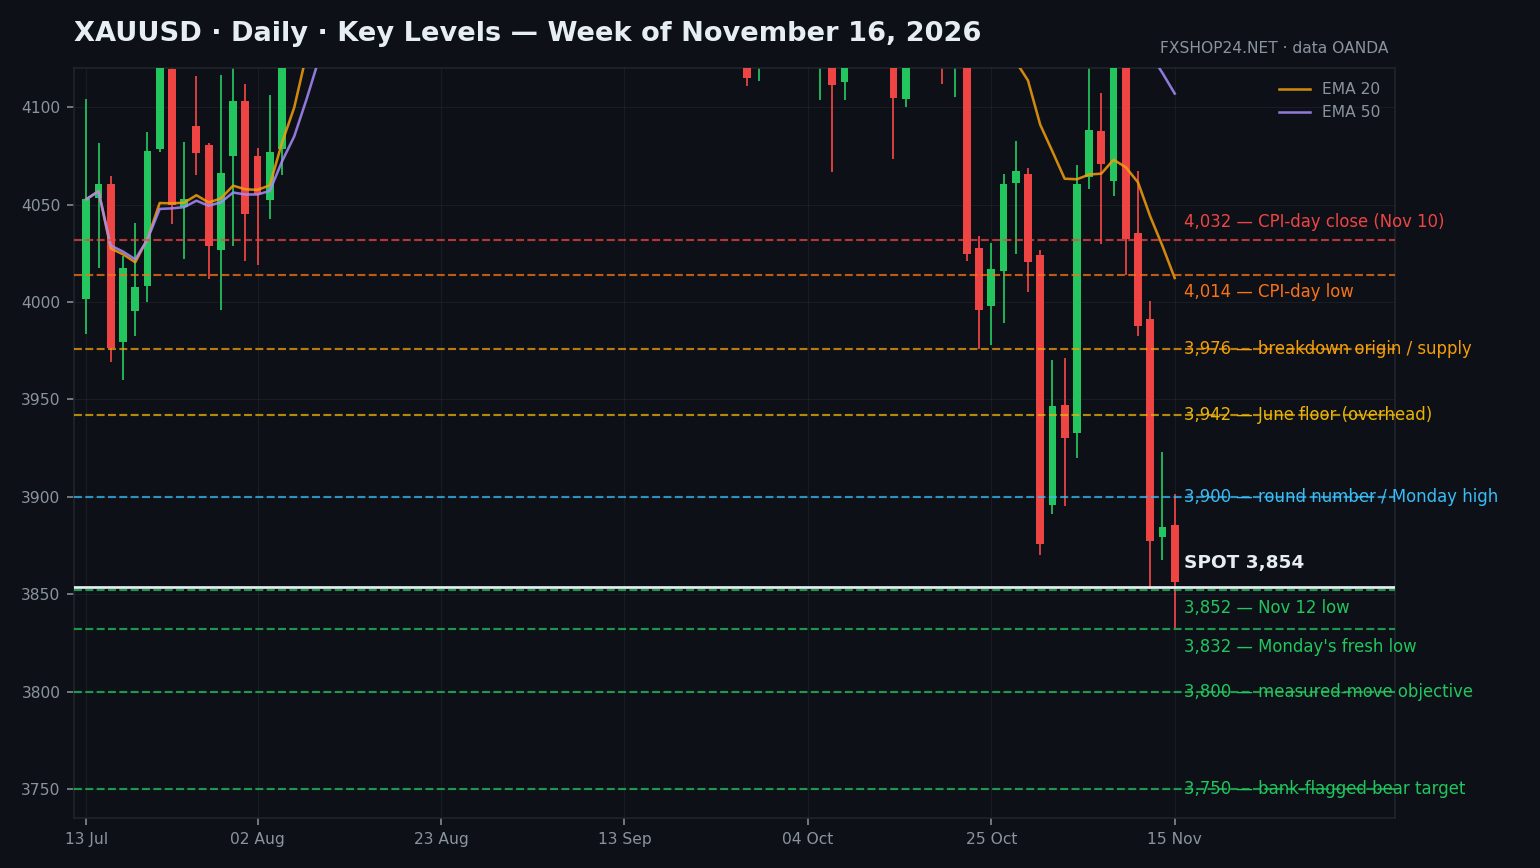
Spot gold trades around 3,854 on Monday morning (November 16), pressing fresh cycle lows after last week’s CPI shock killed the post-election rebound. The sequence was brutal in its efficiency: Monday’s close at 4,141 had finally broken the 4,140–4,150 wall we flagged — then Tuesday’s October CPI printed hot (+0.4% headline vs +0.3% expected; core +0.3% vs +0.2%), and gold was rejected in a single session, closing at 4,033. Thursday added a >3% washout to 3,853 as a parade of Fed officials (Goolsbee calling inflation “uncomfortable”, Logan flagging the need for two more hikes, Warsh’s allies out in force) sent December hike odds toward 85–90% — effectively a done deal unless data turns. Friday’s PPI cooled a touch (+0.3% vs +0.4% expected), which stabilized the tape, but this morning gold slipped to a new low at 3,832 before rebounding.
So the “trend change” confirmed three weeks ago remains the operative frame: price is back below the June floor at 3,942 (overhead again), below the falling 20-day EMA (≈4,012) and 50-day EMA (≈4,108), and daily ATR near $96. What has changed versus mid-October is the macro map: the midterms brought a divided government (gridlock read: softer dollar, softer yields — gold’s best hope), and strategists now openly model divergent 2027 paths — Citi’s baseline (Hormuz shipping normalizes, oil falls to $65–70, disinflation returns) is gold-bullish medium term, while its 30% bear case has gold sliding toward 3,500 if the energy shock persists. This week’s Fed speakers (Chair Warsh himself speaks today) and Wednesday’s FOMC minutes will tell us how much fight the hawks have left.
Key levels
| Level | Type | Why it matters |
|---|---|---|
| 4,013–4,032 | Resistance | Nov 10 (CPI-day) close and low — where sellers reloaded after the hot print |
| 3,976 | Resistance | Nov 11–12 breakdown origin / former support cluster — supply overhead |
| 3,942 | Pivot | The June floor, now resistance again — a reclaim is required to break the sequence of lower highs |
| 3,900 | Resistance | Round number + Monday’s rebound high (3,901) — the first intraday hurdle |
| 3,852–3,832 | Key support | Nov 12 low (3,853) + Monday’s fresh cycle low (3,832) — the front line of the battle |
| 3,800 | Major support | Round number / measured-move objective — a closing break accelerates the decline |
| 3,750 | Major support | Bank-flagged bear target zone (BofA’s 3,750); Citi’s bear case ultimately eyes 3,500 if the Hormuz standoff persists |
Two scenarios
Bearish (base case while below 3,942): the trend is down, December is priced as a near-certain hike, and this week’s Fed calendar (Warsh today, Hammack and Williams Tuesday, the October minutes Wednesday) leans hawkish. If Monday’s low gives way on a closing basis, expect a grind to 3,800 and then 3,750, with any CPI-hangover dollar strength doing the pushing. Invalidation: a daily close back above 3,976.
Bullish (exhaustion and base-building): notice the shape of the lows — 3,870 (Oct 30), 3,853 (Nov 12), 3,832 (today): each new low is shallower and bought back faster, classic downside-exhaustion mechanics in an already-crowded short market. Friday’s PPI cooled, and the market’s own medium-term story (gridlock Congress, potential Hormuz de-escalation, eventual Fed pivot) is friendly. If 3,832 holds and Tuesday’s retail sales soften, the short-covering path runs through 3,900 and 3,942 toward 3,976. Invalidation: a daily close below 3,800.
Calendar watch
- Monday, November 16: Empire State manufacturing (8:30 am ET); Canada CPI. Fed Chair Warsh speaks at 12:00 pm ET (18:00 CET) — the week’s first tone-setter after CPI; any hint on December cadence moves the dollar and gold.
- Tuesday, November 17: October retail sales (8:30 am ET, consensus ≈+0.2–0.5%), import prices, industrial production (9:15 am), NAHB housing index (10:00 am); a heavy Fed slate — Musalem (7:30 am), Waller (9:10 am), Hammack at Brookings (9:30 am), Williams (2:25 pm). Nvidia earnings after the close (risk-sentiment spillover).
- Wednesday, November 18: housing starts and building permits (8:30 am ET), pending home sales (10:00 am); October FOMC minutes at 2:00 pm ET (20:00 CET) — markets want the size of the hawkish bloc beyond Hammack and Cook’s dissent and any discussion of a faster hiking pace.
- Thursday, November 19: weekly jobless claims (8:30 am ET, previous 189k — a very low base), Philly Fed business outlook (8:30 am).
- Friday, November 20: University of Michigan final November sentiment (10:00 am ET) — watch the inflation-expectations component; no top-tier data otherwise.
- Forward markers: October PCE and Q3 GDP second estimate on Wednesday, November 25 (Thanksgiving week); the December 8–9 FOMC with a new dot plot is the next decision.
EA angle
- Volatility regime: daily ATR near $96 — deep expansion. Assume $80–120 ranges; stops and grid steps calibrated for the October calm will be run over.
- News filters: three real events this week — Warsh today (12:00 pm ET), retail sales Tuesday (8:30 am ET), and the FOMC minutes Wednesday (2:00 pm ET / 20:00 CET). Freeze around all three; treat Tuesday’s Fed-speaker stack (especially Hammack and Williams) as a soft-filter window too.
- Trend vs mean-reversion: the tape below falling EMAs with a live December hike is trend-follower territory — the cleaner entries remain rallies that fail into 3,900–3,942 supply. Mean-reversion longs at 3,832/3,800 are scalp-only trades until a genuine higher low prints; no knife-catching below the front line.
- Sizing: halve risk into Wednesday’s minutes. Single headlines are moving gold 1.5–2%, stop slippage is running well beyond backtest norms, and the crowded-short squeeze scenario argues for surviving first, pressing size only after the minutes.
FXShop24 Research Team — educational content, not investment advice. Trading gold? Read our guides on position sizing and gold-specific EA settings on fxshop24.net, and follow @fxshop24 on Telegram for weekly levels and free signals.